
The Federal Mortgage Bank of Nigeria (FMBN) launched a non-interest mortgage product known as Ijarah Muntahia Bittamleek, or lease-to-own, in October 2026. The initiative is intended to give eligible National Housing Fund (NHF) contributors another route towards homeownership. For households that have struggled to access conventional mortgage finance, the announcement is significant—but the practical value will depend on the product’s detailed terms, eligibility rules and the homes available.
FMBN announced the launch on 28 October after a ceremony in Kano. The bank described the product as a lease arrangement through which a customer occupies a property and may acquire ownership after meeting the agreed contractual obligations. This is not the same as receiving a house without cost, and applicants should understand the full payment structure before making a commitment.
How lease-to-own financing is intended to work
Under an Ijarah structure, the customer uses a property under a lease arrangement. The agreement sets out the payments, responsibilities and conditions that apply during the lease period. A transfer of ownership is expected at the end of the arrangement when the contractual requirements have been fulfilled. The precise legal documents and sequence matter, so applicants should request the actual product documentation rather than relying on a short description or a sales presentation.
Prospective applicants should ask who holds legal title during the lease, how the final transfer will be documented, what happens if a payment is missed, and who is responsible for major repairs, insurance or other property-related costs. These questions should be answered in writing.
Who should check eligibility?
FMBN says the product is designed for eligible NHF contributors. A prospective applicant should confirm whether their contribution record is current, how long they must have contributed, which income or employment categories qualify and whether the property location affects eligibility. Applicants should obtain the official checklist directly from FMBN and verify whether applications are open for the particular pilot or property being considered.
Do not assume that every NHF contributor automatically qualifies or that a launch announcement means funds are immediately available to everyone. Product limits, property supply, allocation procedures and processing timelines can affect access.
Calculate the real cost of ownership
Before applying, prepare a household budget that includes any initial contribution, recurring lease payments, legal and documentation costs, valuation charges, service fees, utilities, maintenance and moving expenses. Ask whether payments can change during the term and how the bank treats late payment, early settlement or a change in the customer’s circumstances.
Compare the total amount payable over the full period with the cost of alternative housing options. A lower initial payment does not necessarily mean a lower overall cost. Make sure the instalment remains affordable after food, transport, school fees, healthcare and emergency savings are accounted for.
Inspect the property, not just the finance offer
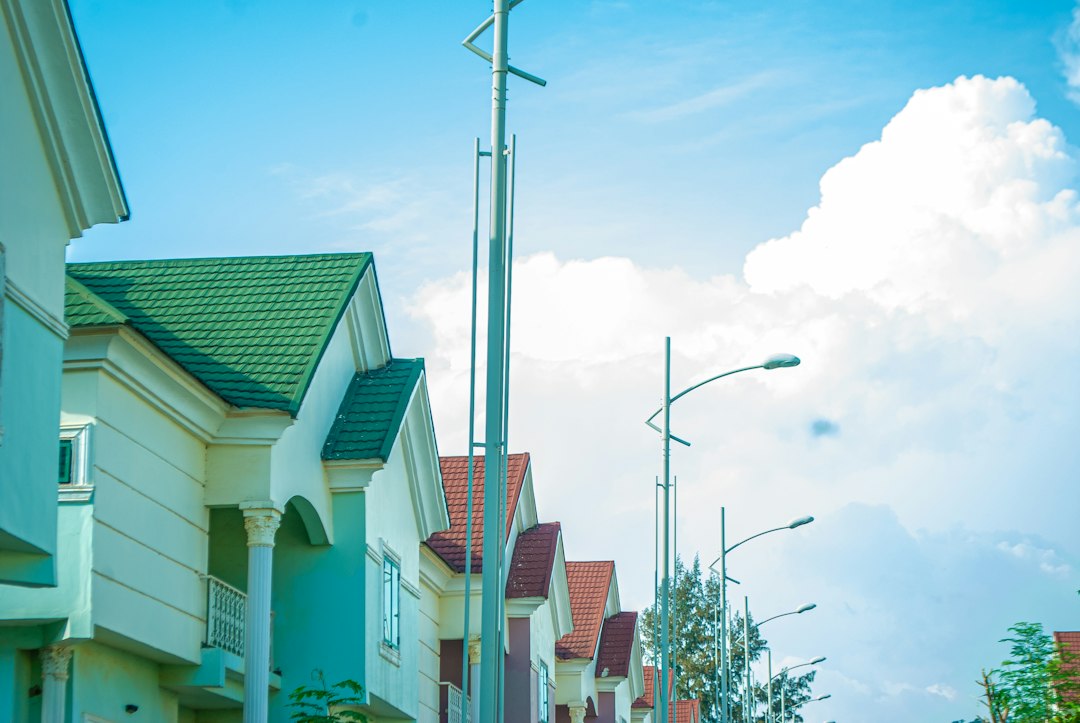
Financing terms cannot compensate for a poor property choice. Inspect the building, road access, drainage, water supply, electricity arrangements, security and nearby services. If the property is in an estate, request the service-charge schedule and identify who maintains shared infrastructure. Have an independent building professional assess visible defects and a property lawyer review the title and transaction documents.
Ask for the exact unit number, approved plans, handover standard and a written list of facilities included in the price. If a home is still under construction, understand the completion milestones and remedies available if delivery is delayed.
Protect yourself during the application process
- Use FMBN’s official channels to confirm current product terms and application status.
- Do not pay unofficial “facilitation” fees into personal accounts.
- Keep copies of contribution records, application forms, receipts and correspondence.
- Have an independent lawyer review the lease and ownership-transfer provisions.
- Do not sign blank forms or rely on verbal promises that are missing from the contract.
What the launch could mean for Nigeria’s housing market
A non-interest mortgage option could widen the range of housing finance available to Nigerians, but its impact will depend on transparent administration, suitable housing supply and repayment terms that match household incomes. The number of homes financed and successfully transferred to beneficiaries will be a more useful measure of impact than the launch ceremony itself.
For now, interested buyers should treat the product as an option to investigate carefully. Confirm eligibility, obtain the full contract, calculate total payments and independently inspect the property before committing.
Source: Federal Mortgage Bank of Nigeria, “FMBN Launches Non-Interest Mortgage Product, Hands Over Keys to Inaugural Beneficiaries of Pilot Project,” 28 October 2026. Read the official announcement.
This article is for general information and is not financial or legal advice. Product terms and eligibility should be confirmed directly with FMBN.